For homeowners with good income and shrinking cash flow
House-poor is not a personality. It is a payment structure.
Good income, disappearing cash flow. Jason Iacovelli has been inside mortgage lending since 1995. The free Money Map places your current mortgage beside a modeled alternative. The numbers do the rest.
What a mortgage payment is actually doing
One loan. Stated assumptions. No mystery numbers.
Illustrative example: $300,000, 30-year fixed mortgage at 5.5%, scheduled principal-and-interest payment of $1,703.37, no extra payments. Figures are rounded and exclude taxes, insurance, and fees.
First payment
$1,375 interest
$328 principal
After 5 years
$277,382 balance
$79,584 interest paid
After 10 years
$247,623 balance
$152,027 interest paid
Your result depends on your balance, rate, remaining term, cash flow, fees, spending, and available product terms.
The UnMortgage Money Map
One free comparison. Three paths. You choose.
The calculator starts with what would help your household most, then models the trade-offs instead of forcing everyone into the same answer.
Put Money in My Pocket
Estimate sustainable monthly cash-flow relief while preserving a modeled payoff target.
Kill My Mortgage
Model the fastest payoff path supported by the assumptions and cash flow you provide.
Best of Both Worlds
Balance a selected amount of monthly relief with a shorter modeled payoff timeline.
The modeled mechanism
The structure changes how cash flow meets the balance
A qualifying alternative generally replaces the current 1st mortgage. It is still a real loan secured by your home. The details matter.
Replace the 1st mortgage
A qualifying 1st-lien line generally takes the place of the existing 1st mortgage.
Route income to the line
Direct deposits lower the outstanding line balance when income arrives.
Use the daily balance
Interest accrues from the outstanding daily balance, so balance movement matters.
Let cash flow do the work
Spending raises the balance again. Positive monthly cash flow creates the net progress.
The honest-broker standard
The current mortgage gets a fair chance to win
Jason entered mortgage lending in 1995. Cancer at 23 changed how he thinks about time, risk, and long-term debt. It did not make him reckless. It made him precise about what a financial decision can cost.
The Money Map compares the current mortgage with the alternative. If keeping the current loan is the better answer, Jason says so.
“I’d rather lose the deal than set you on fire.”
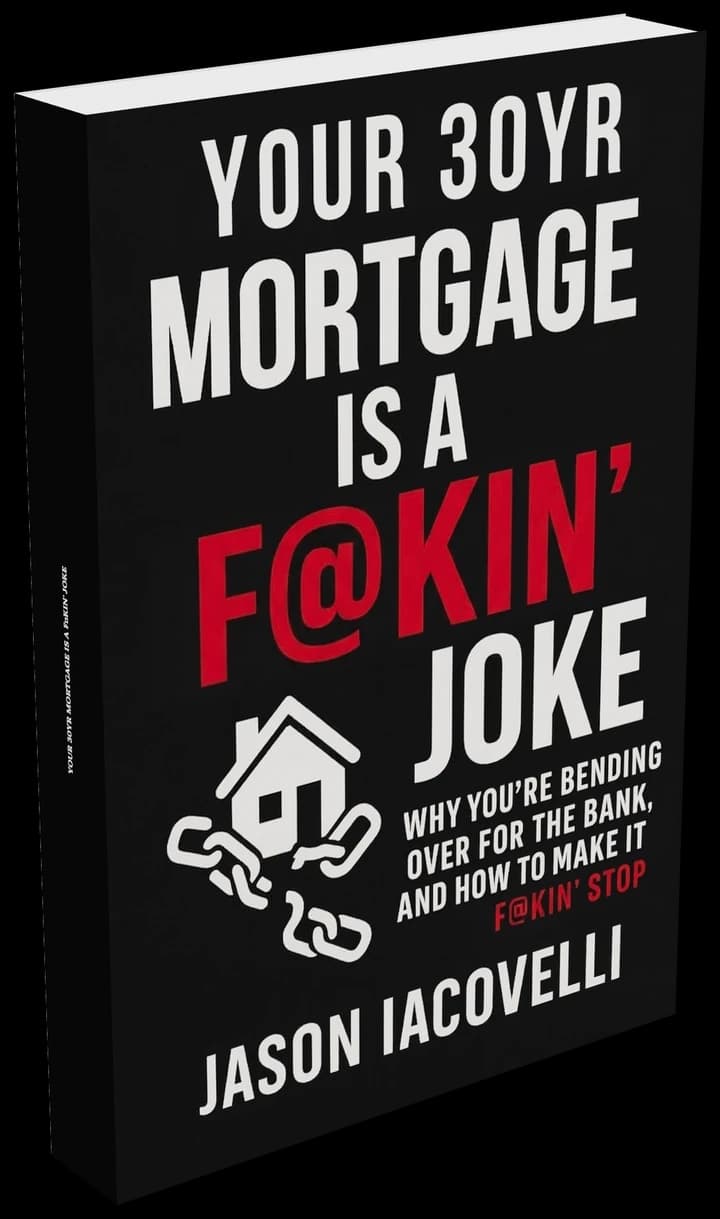
Digital edition • PDF
Your 30yr Mortgage is a F@KIN' Joke
You have made every payment on time. So why does it feel like you are getting nowhere?
The complete digital edition goes deeper into daily-balance interest, automation, risks, and the full comparison framework.
Complete Book - $14.99Get the Free Book PreviewYour mortgage. Your cash flow. Your assumptions.
See what your numbers actually say
Build the preliminary comparison first. If the current mortgage wins, keep it. If the modeled alternative deserves a closer look, booking and application options come after the result.
Build My Free Money Map